October 26, 2026
What the 2027 Winter outlook could mean for Energy Markets
By: Bob Barron, VP, Energy Management, Competitive Power Ventures (CPV)
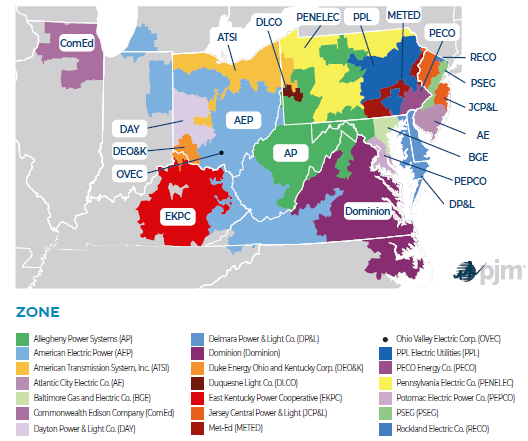
- PJM continues the process of maneuvering through “FERC reconciliation/suggestions” so the Reliability Backstop Auction can proceed. The timing is interesting because the next Base Residual Auction (BRA-2029/2030) is scheduled for December and is likely to result in an additional capacity shortfall from the prior BRA.
- The original RBA was accepted by FERC on September 29, but was suspended for 5 months and was subject to additional modifications/comments from FERC.
- The multi-phase process combines a bilateral contracting period coupled with a central procurement process, allowing PJM to deal with a likely shortfall.
- PJM’s current forecast anticipates a 32,000 MW peak load growth by 2030, consisting primarily of data centers.
NYISO Regulatory Review
- The NYISO updated their market tariffs after a FERC Commission Order was issued on October 19.
- Recent proposed changes to the tariffs include provisions to address the seasonal reliability risks and improve their assessment of seasonal availability of resources. Firm transportation constraints is a key parameter for winter supply metrics.
- The ISO is still facing tight reserve margins even with additional solar resources being deployed and available dispatchable generation remains stagnant.
Market Drivers
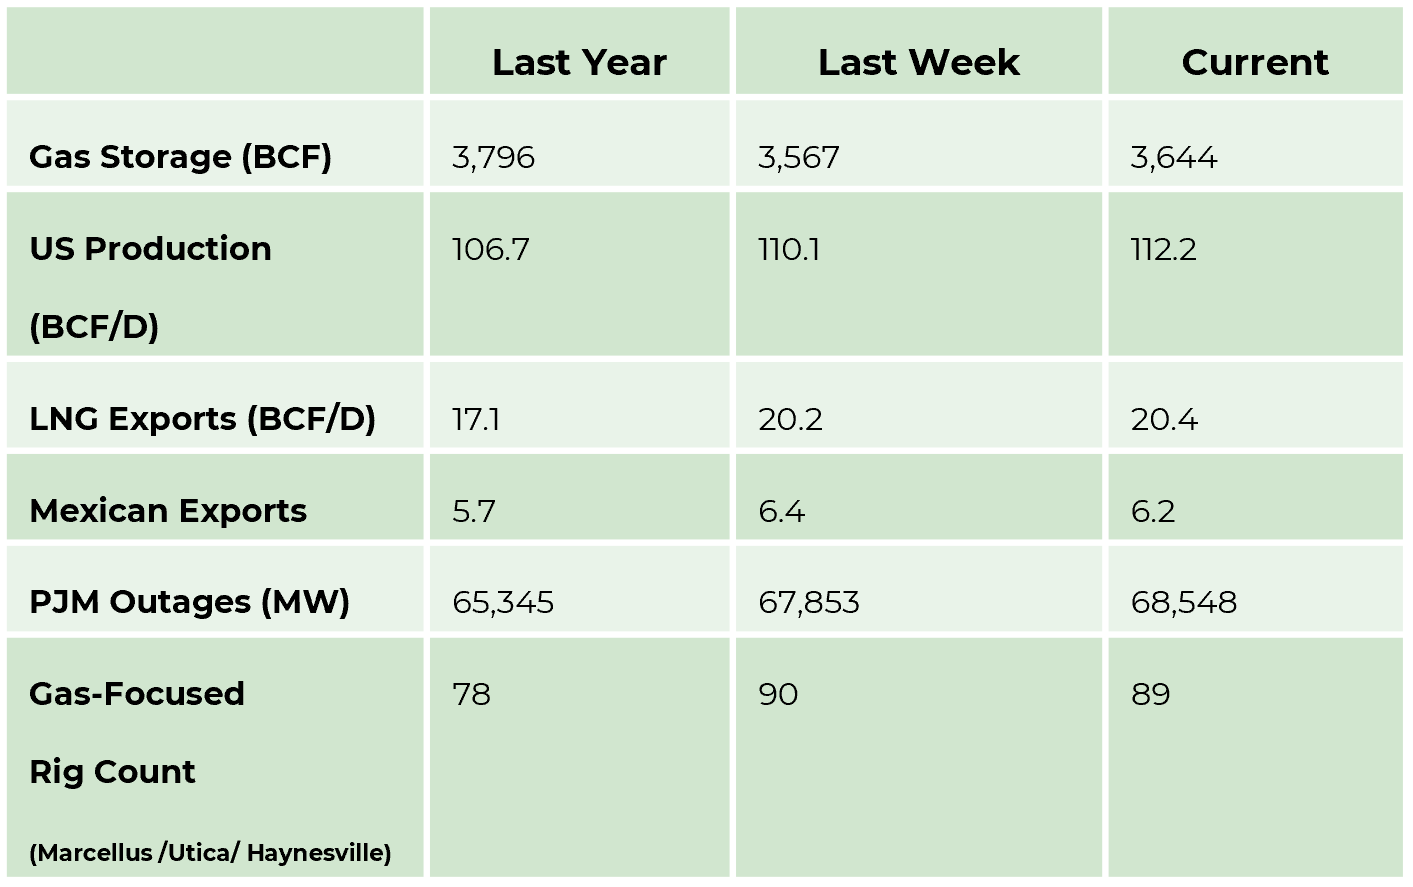
Market Drivers as of October 23, 2026.
- Gas Storage/Year over year difference. A positive number is bearish, and a negative number is bullish.
- Production /Year over year growth/trend is important in the context of demand growth.
- LNG Exports/Year over year growth means demand is growing and should be looked at in comparison to production trend.
- Mexican Exports/Add to LNG Exports to show a trend in exports compared to the production trend.
- PJM Outages- generally seasonal in Spring or Fall/Can support short-term prices.
- Gas Focused Rig Count/Is drilling increasing to grow production versus demand growth. This can be seen as impacting price in the future based on expected load growth.
Energy Market Update
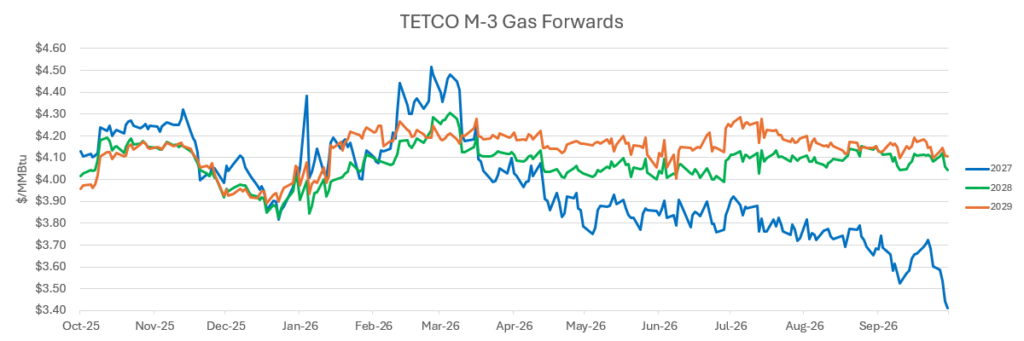
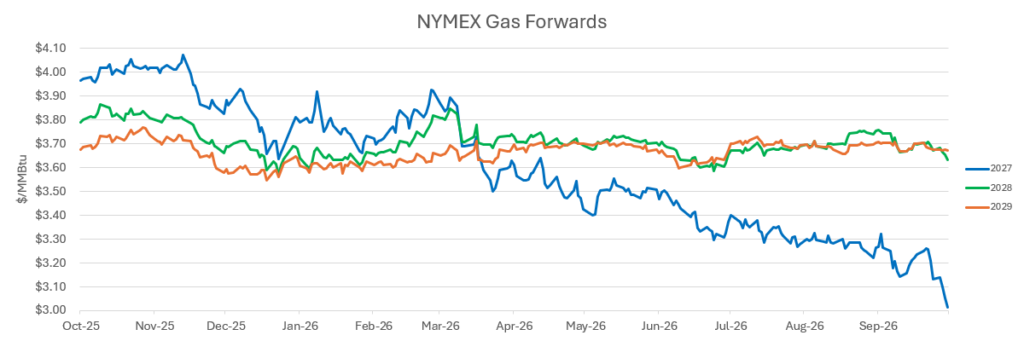
- The natural gas price sell-off continues unabated as production remains strong and expectations of continued warm weather have taken the premium out of the winter. The November NYMEX is near lows of 2020 at $2.67/MMBTU.
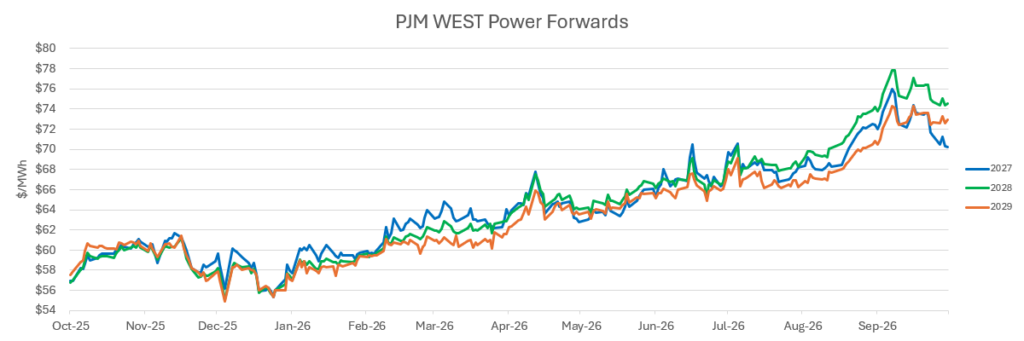
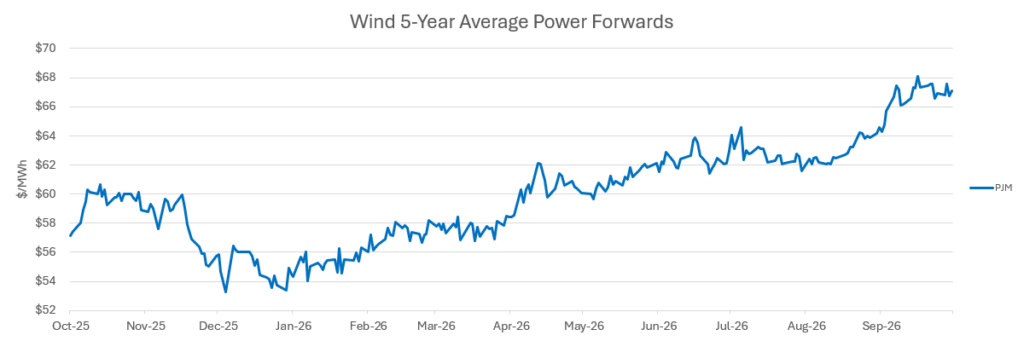
- Power prices have not sold off as hard as natural gas prices but the relentless chatter about the Super El Nino creating a blast furnace warm winter continues to motivate selling across the winter strip and into Calendar/2027.
- The fall outage season is still running strong with almost 70,000 MW out for maintenance after a strong summer of sustained operations by many PJM generating assets.
- Even with the increased power demand natural gas spot prices have been sub $1.50/MMBTU in the northeast which has lowered coal generation.